🛰️ Tesla: SpaceX plant $50 miljard AI-campus - Bullish voor TSLA

Geen tijd om het hele artikel te lezen? Deze bullets vatten het samen.
■ SpaceX wil in Cochise County in Arizona een supercomputer- en AI-campus ontwikkelen met uiteindelijk maximaal negen gebouwen en een geschatte stroomvraag van 6 GW. De aanvraag omvat daarnaast een batterijopslagsysteem van 24 GWh, waardoor energieopslag een essentieel onderdeel van de infrastructuur wordt.
■ Desk-view: wij zien deze ontwikkeling als potentieel bullish voor Tesla, vooral voor Tesla Energy. SpaceX is al een grote Megapack-klant en een Arizona-campus van deze omvang kan de vraag naar Tesla's grootschalige energieopslag verder versnellen, maar een contract voor de volledige 24 GWh is nog niet publiek bevestigd. Wij zetten Tesla daarom op de watchlist, maar nemen gezien de minder gunstige chart niet automatisch een positie in. We bekijken of de koersstructuur voldoende verbetert om toch een kleine positie op een stijging in te nemen.
■ Tesla rapporteerde in de eerste negen maanden van 2026 $626 miljoen omzet uit Megapack-verkopen aan SpaceX. Eind Q3 stond bovendien $729 miljoen aan SpaceX-gerelateerde vorderingen open en bedroeg de deferred revenue uit deze Megapack-contracten $648 miljoen.
■ SpaceX rapporteerde vanuit de koperskant $480 miljoen aan Megapack-aankopen in de eerste negen maanden van 2026, na $506 miljoen in 2025. De verschillende bedragen weerspiegelen een andere boekhoudkundige timing en mogen daarom niet bij elkaar worden opgeteld.
■ De voorgestelde batterijcapaciteit in Arizona bedraagt 24 GWh. Tesla zette in de eerste negen maanden van 2026 wereldwijd 36,0 GWh aan energieopslagproducten uit, waardoor de omvang van het Arizona-plan gelijkstaat aan ongeveer twee derde van Tesla's volledige uitrol over die periode.
■ Tesla Energy behaalde in Q3 $2,881 miljard omzet en $954 miljoen brutowinst. De brutomarge kwam uit op 33,1%, waardoor Energy een steeds belangrijker onderdeel wordt van de winststructuur van Tesla.
■ Een mogelijke combinatie tussen Tesla en SpaceX is inmiddels meer dan alleen marktspeculatie. Beide ondernemingen hebben speciale commissies gevormd om een verdere verdieping van de relatie te onderzoeken, waarbij een mogelijke business combination tot de onderzochte opties behoort. Er is nog geen akkoord en er bestaat geen zekerheid dat uiteindelijk een transactie volgt.
■ Volgens ons maakt de verdere industriële verwevenheid tussen Tesla en SpaceX een toekomstige combinatie strategisch logischer dan voorheen. Energieopslag, AI-infrastructuur, compute, productie en autonome systemen komen steeds dichter bij elkaar te liggen.
■ De chart is minder overtuigend dan de fundamentele ontwikkeling. Tesla heeft een deel van de recente schade hersteld, maar de koersstructuur geeft ons nog onvoldoende reden om zonder verdere bevestiging een positie te openen.
■ Tesla komt daarom op onze watchlist. Wij volgen of de fundamentele verbetering uiteindelijk ook door de chart wordt bevestigd en bekijken dan of een kleine positie op een stijging verantwoord wordt.
Investment View
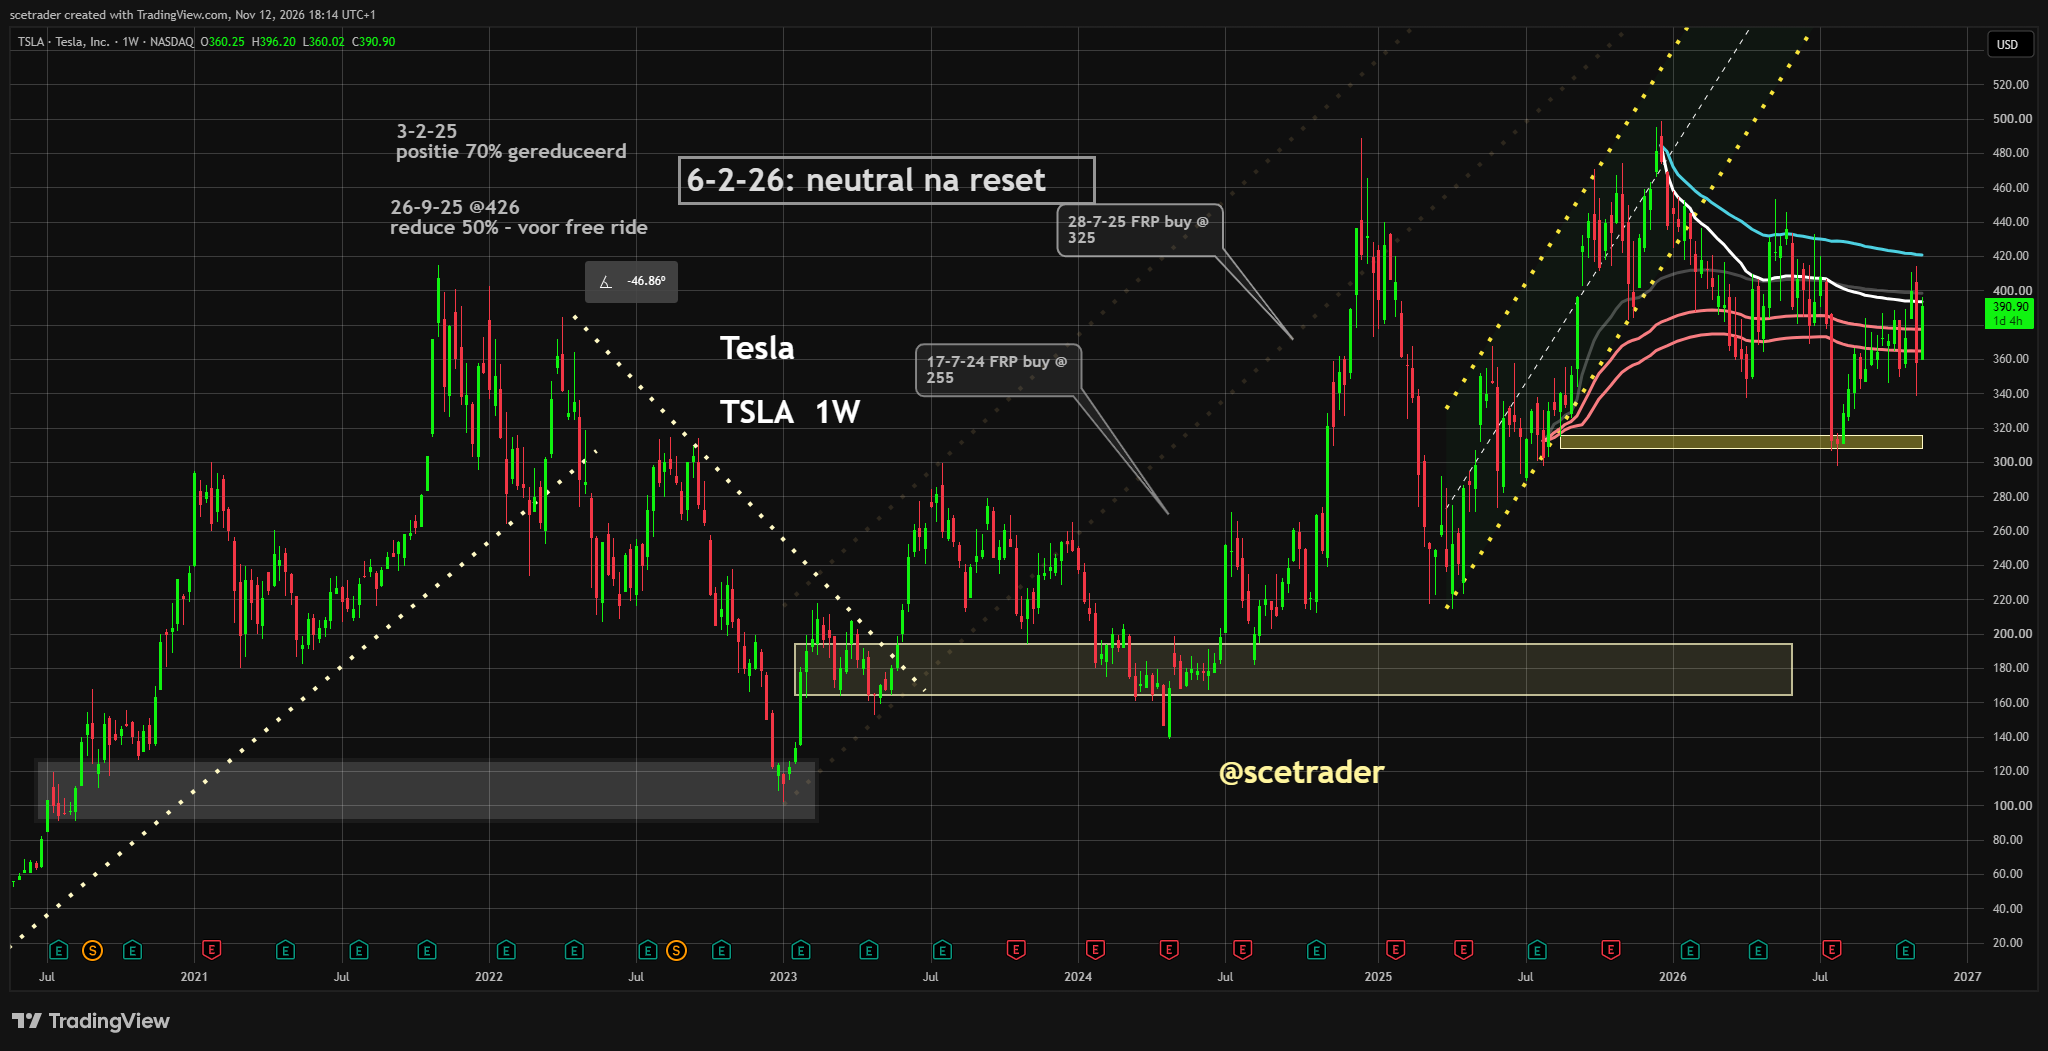
Wij vinden de ontwikkeling in Arizona fundamenteel bullish voor Tesla, maar dat betekent niet dat wij onmiddellijk een positie innemen. De belangrijkste verandering is dat Tesla Energy steeds duidelijker onderdeel wordt van de infrastructuur achter de enorme groei van AI-compute, terwijl SpaceX zich tegelijkertijd ontwikkelt tot een materiële industriële klant van Tesla.
De commerciële relatie is inmiddels groot genoeg om serieus mee te wegen. Tesla realiseerde in de eerste negen maanden van 2026 $626 miljoen omzet uit Megapack-verkopen aan SpaceX, terwijl eind Q3 nog honderden miljoenen dollars aan vorderingen en contractuele verplichtingen openstonden. Daarmee gaat het niet langer om een theoretische samenwerking tussen twee bedrijven rond Elon Musk, maar om een concrete zakelijke relatie met materiële financiële omvang.
De mogelijke 24 GWh batterijopslag in Arizona kan die relatie naar een veel grotere schaal brengen. De voorgestelde opslagcapaciteit staat gelijk aan ongeveer twee derde van alle energieopslag die Tesla in de eerste negen maanden van 2026 wereldwijd heeft uitgerold. Het is daarbij belangrijk dat nog niet publiek is bevestigd dat Tesla de volledige Arizona-order krijgt, waardoor wij deze potentiële omzet niet vooruit willen boeken.
Voor ons verandert hierdoor wel de manier waarop wij Tesla Energy beoordelen. Tesla verkoopt niet alleen batterijen aan elektriciteitsbedrijven en traditionele opslagprojecten, maar kan een steeds belangrijkere leverancier worden voor AI-datacenters waar netcapaciteit, piekvermogen en continuïteit van de stroomvoorziening cruciaal zijn.
Dat creëert een groeimarkt die niet één op één samenvalt met de traditionele automarkt. Wanneer AI-compute blijft toenemen en elektriciteit een beperkende factor wordt, kan grootschalige batterijopslag een structureel onderdeel worden van nieuwe datacenters.
Daarnaast vinden wij de ontwikkeling rond SpaceX strategisch interessant. Een verdere combinatie tussen Tesla en SpaceX wordt formeel onderzocht en een volledige business combination behoort tot de mogelijke structuren. Dat betekent nog niet dat een fusie komt, maar het scenario is veel concreter dan wanneer er alleen marktspeculatie zou bestaan.
Het Arizona-project vergroot volgens ons de industriële logica achter een nauwere relatie. SpaceX bouwt steeds grotere AI-infrastructuur, terwijl Tesla een belangrijk onderdeel van de energiearchitectuur kan leveren. Tegelijk bewegen beide ondernemingen richting steeds meer verticale integratie rond energie, compute, productie en autonome systemen.
Een mogelijke combinatie is echter niet automatisch positief voor Tesla-aandeelhouders. De waardering van SpaceX, de ruilverhouding, governance en eventuele verwatering bepalen uiteindelijk of zo'n transactie waarde toevoegt. Wij nemen een fusie daarom niet als zekerheid op in onze Tesla-these.
Fundamenteel vinden wij het totaalbeeld wel sterker geworden. Tesla Energy ontwikkelt zich tot een serieus winstcentrum en AI-infrastructuur kan daar een nieuwe structurele groeimotor aan toevoegen.
De chart geeft ons alleen nog niet dezelfde overtuiging. Daarom zetten wij Tesla op de watchlist in plaats van direct een koopbesluit te nemen. Wij kijken of de technische structuur voldoende verbetert om een kleine positie op een stijging te rechtvaardigen.
Arizona kan een van de grootste AI-campussen worden
De aanvraag in Cochise County beslaat ongeveer 747 acres en voorziet uiteindelijk in maximaal negen grote computegebouwen. De totale elektriciteitsvraag kan bij volledige uitbouw richting ongeveer 6 GW gaan, waarbij het project in verschillende fases wordt ontwikkeld.
Voor Arizona is een investering van ongeveer $50 miljard genoemd. Daarnaast moet enkele miljarden dollars worden geïnvesteerd in elektriciteitsinfrastructuur, waaronder transmissie en aansluitingen die nodig zijn om de enorme vermogensvraag mogelijk te maken.
Daarmee is dit geen traditioneel datacenterproject. Een campus van meerdere gigawatts wordt feitelijk een eigen industrieel energiesysteem waarin opslag, transmissie, koeling en noodvoorzieningen net zo bepalend worden als de computers zelf.
Het project is nog niet volledig definitief. Vergunningen, infrastructuur en verdere goedkeuringen moeten nog worden afgerond, waardoor zowel de timing als de uiteindelijke schaal kan veranderen.
De 24 GWh batterijopslag is voor Tesla het belangrijkste onderdeel
Het ontwerp omvat ongeveer 24 GWh aan batterijopslag. Zo'n systeem kan een belangrijke rol spelen bij het stabiliseren van de enorme stroomvraag van een AI-campus en het opvangen van pieken wanneer het elektriciteitsnet onvoldoende capaciteit levert.
Voor Tesla is vooral de schaal relevant. De onderneming zette in de eerste negen maanden van 2026 wereldwijd 36,0 GWh aan energieopslagproducten uit. Een project van 24 GWh is daarmee uitzonderlijk groot ten opzichte van Tesla's huidige jaarlijkse volumes.
Dat betekent niet dat Tesla alle capaciteit in één jaar zou leveren. De campus wordt in fases ontwikkeld en ook batterijopslag zou daardoor waarschijnlijk over meerdere jaren worden geïnstalleerd.
Daarnaast is de volledige 24 GWh nog niet formeel aan Tesla toegekend. De bestaande commerciële relatie en het gebruik van Megapacks binnen andere SpaceX-projecten maken Tesla wel een logische potentiële leverancier.
SpaceX is al een grote klant van Tesla Energy
De samenwerking tussen Tesla en SpaceX bestaat al op aanzienlijke schaal. Tesla rapporteerde $221 miljoen omzet uit SpaceX-Megapacks in Q3 en $626 miljoen over de eerste negen maanden van 2026.
Aan het einde van september had Tesla $729 miljoen aan SpaceX-gerelateerde Megapack-vorderingen op de balans. Een groot deel daarvan hield verband met Megapacks die nog niet waren geleverd, terwijl ook honderden miljoenen dollars aan deferred revenue openstonden.
Dat vinden wij belangrijker dan alleen een verwijzing naar Megapacks in een nieuw projectplan. De commerciële relatie bestaat al en SpaceX heeft aantoonbaar voor grote bedragen Tesla-opslag gekocht.
Arizona kan daardoor een volgende fase worden van een samenwerking die financieel al bewezen is. Wanneer Tesla daadwerkelijk een groot deel van de 24 GWh mag leveren, kan de relatie met SpaceX opnieuw aanzienlijk groter worden.
Tesla Energy wordt financieel steeds belangrijker
Tesla Energy behaalde in Q3 $2,881 miljard omzet. De brutowinst bedroeg $954 miljoen, waarmee de brutomarge uitkwam op 33,1%.
Dat vinden wij relevant omdat Tesla nog vaak voornamelijk wordt bekeken door de bril van auto's, robotaxi en AI. Energy is inmiddels echter een miljardenbedrijf met een relatief hoge brutomarge en levert een steeds grotere bijdrage aan de totale resultaten.
Over de eerste negen maanden van 2026 kwam de omzet van Energy uit op $8,428 miljard. De brutowinst bedroeg over dezelfde periode $2,546 miljard, waardoor deze divisie inmiddels voldoende schaal heeft om echt verschil te maken voor Tesla.
AI-infrastructuur kan daar een nieuwe groeipoot aan toevoegen. Wanneer hyperscalers en andere AI-operators steeds grotere hoeveelheden batterijopslag nodig hebben, kan Tesla via Megapack indirect steeds meer exposure krijgen naar de AI-capexcyclus.
Een combinatie met SpaceX wordt daadwerkelijk onderzocht
Een mogelijke combinatie tussen Tesla en SpaceX is niet langer alleen een onderwerp voor speculatie. Beide bedrijven hebben speciale commissies ingesteld om mogelijkheden voor een nauwere relatie te onderzoeken.
Daarbij behoort ook een mogelijke business combination tot de opties. Er is echter nog geen overeengekomen transactie, waardering of ruilverhouding en het is evenmin zeker dat uiteindelijk daadwerkelijk een overeenkomst wordt bereikt.
Wij vinden het wel relevant dat het proces formeel bestaat. Dat maakt een toekomstige combinatie concreter dan wanneer er alleen strategische overeenkomsten tussen de activiteiten zouden zijn.
Voor onze waardering van Tesla nemen wij een fusie voorlopig niet als basisscenario mee. Daarvoor ontbreken nog te veel belangrijke gegevens over de financiële voorwaarden en de gevolgen voor bestaande aandeelhouders.
Arizona versterkt de strategische logica
Het nieuwe project maakt volgens ons wel duidelijker waarom Tesla en SpaceX operationeel steeds dichter bij elkaar kunnen komen. SpaceX heeft veel energieopslag nodig voor AI-compute en Tesla heeft precies daarvoor een product waarvan de productie snel wordt opgeschaald.
Ook financieel zijn de banden inmiddels groter. Tesla heeft daarnaast kapitaal in SpaceX geïnvesteerd, waardoor de relatie verder gaat dan alleen leverancier en klant.
Een gecombineerde onderneming zou activiteiten rond ruimtevaart, satellietcommunicatie, AI-compute, batterijopslag, elektrische voertuigen, autonomie en grootschalige productie onder één dak brengen. Dat levert theoretisch veel mogelijkheden op voor verticale integratie.
De economische voorwaarden blijven echter beslissend. Een strategisch interessante combinatie kan voor Tesla-aandeelhouders alsnog ongunstig zijn wanneer de waardering of verwatering niet aantrekkelijk is.
De chart overtuigt minder dan de fundamentele ontwikkeling
Technisch zijn wij voorzichtiger dan fundamenteel. Tesla heeft na de recente correctie een herstel laten zien, maar de koersstructuur geeft ons nog onvoldoende zekerheid dat een nieuwe duurzame stijging al is begonnen.
Juist bij Tesla vinden wij het belangrijk om fundamenteel enthousiasme niet automatisch te vertalen naar een directe koop. Het aandeel kan zeer grote bewegingen maken en een slechte entry kan daardoor snel een forse drawdown opleveren.
Wij willen eerst meer bevestiging dat kopers hogere niveaus kunnen vasthouden. Een duidelijke verbetering van de koersstructuur of een gecontroleerde terugval waarbij belangrijke steun standhoudt, zou de verhouding tussen risico en mogelijk rendement verbeteren.
Daarom plaatsen wij Tesla op de watchlist. We willen het aandeel niet missen wanneer het fundamentele verhaal verder verbetert, maar hoeven tegelijkertijd niet onmiddellijk in te stappen zolang de chart nog geen duidelijke bevestiging geeft.
Wat de visie kan veranderen
Een duidelijk betere technische structuur kan onze houding snel veranderen. Wanneer Tesla belangrijke weerstand weet te doorbreken en hogere niveaus vervolgens weet vast te houden, wordt een kleine positie op een stijging voor ons interessanter.
Fundamenteel letten wij vooral op een eventuele bevestiging van Tesla als leverancier voor Arizona. Wanneer duidelijk wordt dat Tesla daadwerkelijk een materieel deel van de voorgestelde 24 GWh mag leveren, wordt de Energy-these opnieuw sterker.
Daarnaast volgen wij de mogelijke combinatie met SpaceX. Nieuwe informatie over de structuur, waardering of voorwaarden van zo'n transactie kan de beleggingscase sterk veranderen, zowel positief als negatief.
Tot die tijd blijft Tesla op de watchlist. Wij bekijken of fundamentele verbetering en technische bevestiging voldoende bij elkaar komen om een kleine positie op een stijging in te nemen.
Conclusie
Het nieuwe SpaceX-project in Arizona is voor ons meer dan alleen een groot datacenter. De combinatie van maximaal ongeveer 6 GW aan compute en 24 GWh geplande batterijopslag laat zien hoe groot de energiebehoefte van de volgende generatie AI-infrastructuur wordt.
Tesla kan daarvan direct profiteren via Megapack. SpaceX is nu al een grote klant en Tesla heeft in de eerste negen maanden van 2026 honderden miljoenen dollars omzet uit deze commerciële relatie geboekt.
De mogelijke 24 GWh in Arizona kan de samenwerking naar een aanzienlijk grotere schaal brengen. Een definitief contract waarbij Tesla de volledige batterijcapaciteit levert, is nog niet bekendgemaakt en daarom nemen wij die omzet nog niet als zekerheid mee.
Tegelijk groeit Tesla Energy zelf snel uit tot een materiële winstbron. Met miljarden aan omzet, een brutomarge boven 30% en snel stijgende productiecapaciteit wordt energieopslag steeds belangrijker naast de traditionele autoactiviteiten.
Ook het mogelijke samengaan met SpaceX verdient meer aandacht. Beide ondernemingen onderzoeken formeel manieren om de relatie verder te verdiepen en een volledige business combination behoort tot de mogelijke scenario's.
Volgens ons maakt de verdere industriële verwevenheid tussen Tesla en SpaceX een combinatie strategisch logischer. Dat betekent echter niet dat een fusie zeker is of automatisch positief uitpakt voor bestaande Tesla-aandeelhouders.
Fundamenteel zien wij de ontwikkelingen daarom als bullish voor Tesla. Vooral Tesla Energy kan profiteren wanneer AI-datacenters steeds grotere hoeveelheden opslag nodig hebben en SpaceX zijn compute-infrastructuur verder opschaalt.
De chart is op dit moment minder gunstig. Daardoor willen wij niet uitsluitend op basis van het nieuws een positie openen en houden wij technische discipline belangrijk.
Tesla komt daarom op onze watchlist. Wij bekijken of de koersstructuur voldoende verbetert om toch een kleine positie op een stijging in te nemen.
🔵 English version
Tesla $TSLA: SpaceX megacampus strengthens the Energy thesis, but the chart keeps us on the watchlist
No time to read the full article? These bullets summarize it.
■ SpaceX plans to develop a major supercomputer and AI campus in Cochise County, Arizona, potentially comprising as many as nine buildings with an estimated power requirement of up to 6 GW. The application also includes a 24 GWh battery energy storage system, making storage an essential part of the infrastructure.
■ Desk view: we see this development as potentially bullish for Tesla, particularly Tesla Energy. SpaceX is already a major Megapack customer and an Arizona campus of this scale could further accelerate demand for Tesla's grid-scale storage products, although no public contract has yet confirmed that Tesla will supply the full 24 GWh. We are therefore placing Tesla on the watchlist rather than automatically taking a position given the less favorable chart. We will assess whether an improving technical structure justifies taking a small position for an upside move.
■ Tesla recognized $626 million of revenue from Megapack sales to SpaceX during the first nine months of 2026. At the end of Q3, SpaceX-related receivables stood at $729 million and deferred revenue related to these Megapack contracts was $648 million.
■ From the buyer side, SpaceX recorded $480 million of Megapack purchases during the first nine months of 2026 after $506 million in 2025. The figures reflect different accounting timing and should therefore not be added together.
■ The proposed Arizona battery system totals 24 GWh. Tesla deployed 36.0 GWh of energy storage products worldwide during the first nine months of 2026, meaning the proposed Arizona capacity is equivalent to roughly two-thirds of Tesla's entire deployment over that period.
■ Tesla Energy generated $2.881 billion of Q3 revenue and $954 million of gross profit. Gross margin reached 33.1%, making Energy an increasingly important part of Tesla's earnings structure.
■ A potential combination between Tesla and SpaceX is now more than market speculation. Both companies have formed special committees to evaluate a deeper relationship, with a possible business combination among the structures being considered. No agreement exists and there is no certainty that a transaction will ultimately occur.
■ In our view, the increasing industrial links between Tesla and SpaceX make a future combination strategically more logical than before. Energy storage, AI infrastructure, compute, manufacturing and autonomous systems are increasingly moving closer together.
■ The chart is less compelling than the fundamental development. Tesla has recovered part of the recent damage, but the technical structure does not yet provide enough confirmation for us to open a position without further evidence.
■ Tesla therefore moves onto our watchlist. We will monitor whether the improving fundamental story is ultimately confirmed by the chart and then consider whether a small upside position becomes justified.
Investment View
We view the Arizona development as fundamentally bullish for Tesla, but that does not mean we automatically take a position. The main change is that Tesla Energy is becoming an increasingly visible part of the infrastructure required for the enormous expansion of AI compute, while SpaceX is simultaneously becoming a material industrial customer for Tesla.
The commercial relationship is already large enough to matter. Tesla generated $626 million of Megapack revenue from SpaceX during the first nine months of 2026, while hundreds of millions of dollars of receivables and contractual obligations remained outstanding at the end of Q3. This is therefore no longer a theoretical relationship between two companies associated with Elon Musk, but a meaningful commercial connection.
The potential 24 GWh of battery storage in Arizona could take that relationship to a much larger scale. The proposed capacity is equivalent to roughly two-thirds of all energy storage Tesla deployed worldwide during the first nine months of 2026. Tesla has not yet publicly been awarded the entire Arizona requirement, which means we do not want to treat that potential revenue as secured.
This nevertheless changes how we view Tesla Energy. Tesla is no longer selling batteries only to utilities and traditional storage projects, but can increasingly become an important supplier to AI data centers where grid capacity, peak demand and continuity of electricity supply are critical.
That creates a growth market that does not directly follow the traditional automotive cycle. If AI compute continues expanding and electricity remains a limiting factor, large-scale battery storage could become a structural component of new data centers.
We also find the SpaceX development strategically important. A deeper combination between Tesla and SpaceX is formally being evaluated and a full business combination is among the possible structures under consideration. That does not mean a merger will happen, but the scenario is materially more concrete than pure market speculation.
The Arizona project strengthens the industrial logic behind a closer relationship in our view. SpaceX is building increasingly large AI infrastructure while Tesla can supply an important component of the underlying energy architecture. Both businesses are also moving toward greater vertical integration across energy, compute, manufacturing and autonomous systems.
A combination would not automatically be positive for Tesla shareholders. SpaceX's valuation, the exchange ratio, governance structure and potential dilution would ultimately determine whether such a transaction creates value. We therefore do not treat a merger as a certainty in our Tesla thesis.
Fundamentally, however, we believe the overall picture has improved. Tesla Energy is developing into a meaningful profit center and AI infrastructure could add another structural source of growth.
The chart does not yet provide the same level of conviction. We are therefore putting Tesla on the watchlist rather than immediately taking a position. We will assess whether the technical structure improves sufficiently to justify a small position for an upside move.
Arizona could become one of the largest AI campuses
The Cochise County application covers approximately 747 acres and ultimately allows for as many as nine major compute buildings. Total electricity demand could rise toward roughly 6 GW at full build-out, with the campus being developed in several phases.
An investment of approximately $50 billion has been associated with the Arizona project. Several billion dollars of additional electricity infrastructure would also be required to support transmission and grid connections for such enormous power demand.
This is therefore not a conventional data center development. A multi-gigawatt campus effectively becomes its own industrial energy system in which storage, transmission, cooling and backup capacity become as important as the computers themselves.
The project is not yet fully final. Permits, infrastructure and additional approvals remain necessary, meaning both the timing and eventual size can still change.
The 24 GWh battery system is the key element for Tesla
The design includes approximately 24 GWh of battery storage. Such a system could play a major role in stabilizing the enormous electricity requirements of an AI campus and managing demand peaks when grid capacity is insufficient.
For Tesla, the scale is what matters most. The company deployed 36.0 GWh of energy storage products worldwide during the first nine months of 2026. A 24 GWh project is therefore exceptionally large relative to Tesla's current deployment volumes.
This does not mean Tesla would deliver all capacity within a single year. The campus is being developed in phases and the battery infrastructure would likely also be installed over several years.
The full 24 GWh has also not been formally awarded to Tesla. The existing commercial relationship and the use of Megapacks at other SpaceX projects nevertheless make Tesla a logical potential supplier.
SpaceX is already a major Tesla Energy customer
The relationship between Tesla and SpaceX already exists on a substantial scale. Tesla recognized $221 million of revenue from SpaceX Megapacks in Q3 and $626 million during the first nine months of 2026.
At the end of September, Tesla had $729 million of SpaceX-related Megapack receivables on its balance sheet. A large portion related to Megapacks that had not yet been delivered, while hundreds of millions of dollars of deferred revenue also remained outstanding.
We find this much more important than simply seeing Megapacks referenced in a new project design. The commercial relationship already exists and SpaceX has demonstrably purchased substantial amounts of Tesla storage.
Arizona could therefore become the next phase of a relationship that is already financially proven. If Tesla ultimately supplies a major share of the 24 GWh requirement, the scale of the relationship could increase significantly.
Tesla Energy is becoming financially more important
Tesla Energy generated $2.881 billion of revenue in Q3. Gross profit reached $954 million, producing a gross margin of 33.1%.
This matters because Tesla is still often viewed mainly through automobiles, robotaxi and AI. Energy has now become a multibillion-dollar operation with a relatively strong gross margin and an increasingly meaningful contribution to group results.
During the first nine months of 2026, Energy generated $8.428 billion of revenue. Gross profit reached $2.546 billion over the same period, giving the division sufficient scale to materially influence Tesla's financial profile.
AI infrastructure could add another growth engine. If hyperscalers and other AI operators increasingly require large-scale battery storage, Tesla could gain indirect exposure to the AI capital expenditure cycle through Megapack.
A SpaceX combination is genuinely being evaluated
A potential combination between Tesla and SpaceX is no longer merely a subject of market speculation. Both companies have established special committees to evaluate options for a closer relationship.
A possible business combination is among the structures under consideration. There is still no agreed transaction, valuation or exchange ratio, and there is no certainty that an agreement will ultimately be reached.
We nevertheless consider the existence of the formal process relevant. It makes a future combination more concrete than if investors were relying solely on strategic similarities between the two businesses.
We do not currently include a merger in our base-case Tesla valuation. Too many important details remain unknown regarding the financial terms and consequences for existing shareholders.
Arizona strengthens the strategic rationale
The new project makes it easier to understand why Tesla and SpaceX could move closer operationally. SpaceX requires substantial energy storage for AI compute and Tesla produces exactly the type of product required to support that infrastructure.
The financial relationship has also expanded. Tesla has invested capital in SpaceX, meaning the connection now extends beyond a conventional supplier-customer arrangement.
A combined company could bring spaceflight, satellite communications, AI compute, battery storage, electric vehicles, autonomy and large-scale manufacturing under a single corporate structure. In theory, this could create significant opportunities for vertical integration.
The economic terms would still be decisive. A strategically attractive transaction could nevertheless be unfavorable to Tesla shareholders if the valuation or dilution is not compelling.
The chart is less convincing than the fundamentals
Technically, we remain more cautious than we are fundamentally. Tesla has recovered following the recent correction, but the price structure does not yet give us enough confidence that a new durable advance has begun.
With Tesla, we believe it is particularly important not to convert fundamental enthusiasm automatically into an immediate purchase. The shares can make very large moves and a poor entry can quickly produce a meaningful drawdown.
We first want greater evidence that buyers can sustain higher levels. A clearer improvement in the price structure or a controlled pullback that successfully holds important support would improve the risk-reward profile.
Tesla therefore goes onto our watchlist. We do not want to miss the shares if the fundamental story continues to strengthen, but we also do not need to enter immediately while the chart still lacks clear confirmation.
What could change our view
A materially better technical structure could change our stance quickly. If Tesla breaks important resistance and subsequently holds higher levels, a small upside position becomes more interesting to us.
Fundamentally, we are watching for confirmation that Tesla will supply Arizona. If Tesla is awarded a material share of the proposed 24 GWh requirement, the Energy thesis would strengthen again.
We are also monitoring the potential combination with SpaceX. New information regarding the structure, valuation or terms of such a transaction could materially change the investment case in either direction.
Until then, Tesla remains on our watchlist. We will assess whether improving fundamentals and technical confirmation align sufficiently to justify taking a small position for an upside move.
Conclusion
The new SpaceX project in Arizona is more than simply another large data center in our view. The combination of up to roughly 6 GW of compute and 24 GWh of planned battery storage demonstrates the scale of energy infrastructure required by the next generation of AI.
Tesla can benefit directly through Megapack. SpaceX is already a major customer and Tesla generated hundreds of millions of dollars of revenue from the commercial relationship during the first nine months of 2026.
The potential 24 GWh in Arizona could take the relationship to a much larger scale. A definitive contract awarding Tesla the entire battery requirement has not yet been announced, so we do not treat that revenue as secured.
Tesla Energy itself is also becoming an increasingly material profit contributor. With billions of dollars of revenue, gross margins above 30% and rapidly expanding production capacity, energy storage is becoming much more important alongside Tesla's traditional automotive operations.
A potential combination with SpaceX also deserves greater attention. Both companies are formally evaluating ways to deepen the relationship and a full business combination is among the possible scenarios.
In our view, the increasing industrial links between Tesla and SpaceX make a future combination strategically more logical. This does not mean a merger is certain or automatically beneficial to existing Tesla shareholders.
Fundamentally, we therefore see these developments as bullish for Tesla. Tesla Energy in particular could benefit if AI data centers increasingly require large amounts of battery storage while SpaceX continues expanding its compute infrastructure.
The chart is less favorable at the moment. We therefore do not want to open a position solely because of the news and continue to place significant weight on technical discipline.
Tesla moves onto our watchlist. We will assess whether the price structure improves sufficiently to justify taking a small position for an upside move.
Disclaimer Aan de door ons opgestelde informatie kan op geen enkele wijze rechten worden ontleend. Alle door ons verstrekte informatie en analyses zijn geheel vrijblijvend. Alle consequenties van het op welke wijze dan ook toepassen van de informatie blijven volledig voor uw eigen rekening.
Wij aanvaarden geen aansprakelijkheid voor de mogelijke gevolgen of schade die zouden kunnen voortvloeien uit het gebruik van de door ons gepubliceerde informatie. U bent zelf eindverantwoordelijk voor de beslissingen die u neemt met betrekking tot uw beleggingen.


