Recticel: Sterke outlook, maar weerstand ook in zicht

Geen tijd om het volledige artikel te lezen? Gebruik dan de vijf onderstaande bullets voor de belangrijkste punten.
■ Recticel rapporteerde een sterke eerste helft, met duidelijke operationele versnelling.
■ De outlook voor heel 2026 is stevig en wijst op voortzetting van het betere winsttempo.
■ Als wij het aandeel zouden hebben, zouden wij het vasthouden.
■ Wij zouden nu niet bijkopen, omdat de koers weerstand nadert.
■ De kans op een hogere start is aanwezig, maar voor extra koopkracht willen wij eerst een uitbraak of betere terugval zien.
Recticel kwam met een sterke update over de eerste helft van 2026. Vooral het tweede kwartaal liet duidelijke versnelling zien. De groei was breed gedragen over de belangrijkste regio’s en kwam zowel uit Insulation Boards als Insulated Panels.
Daarnaast meldde Recticel dat de Amerikaanse uitbreiding volgens plan verloopt en dat de nieuwe recyclagefabriek in België is opgestart. Daarmee gaat het rapport niet alleen over betere cijfers, maar ook over uitvoering van de strategische groeiplannen.
Investment view
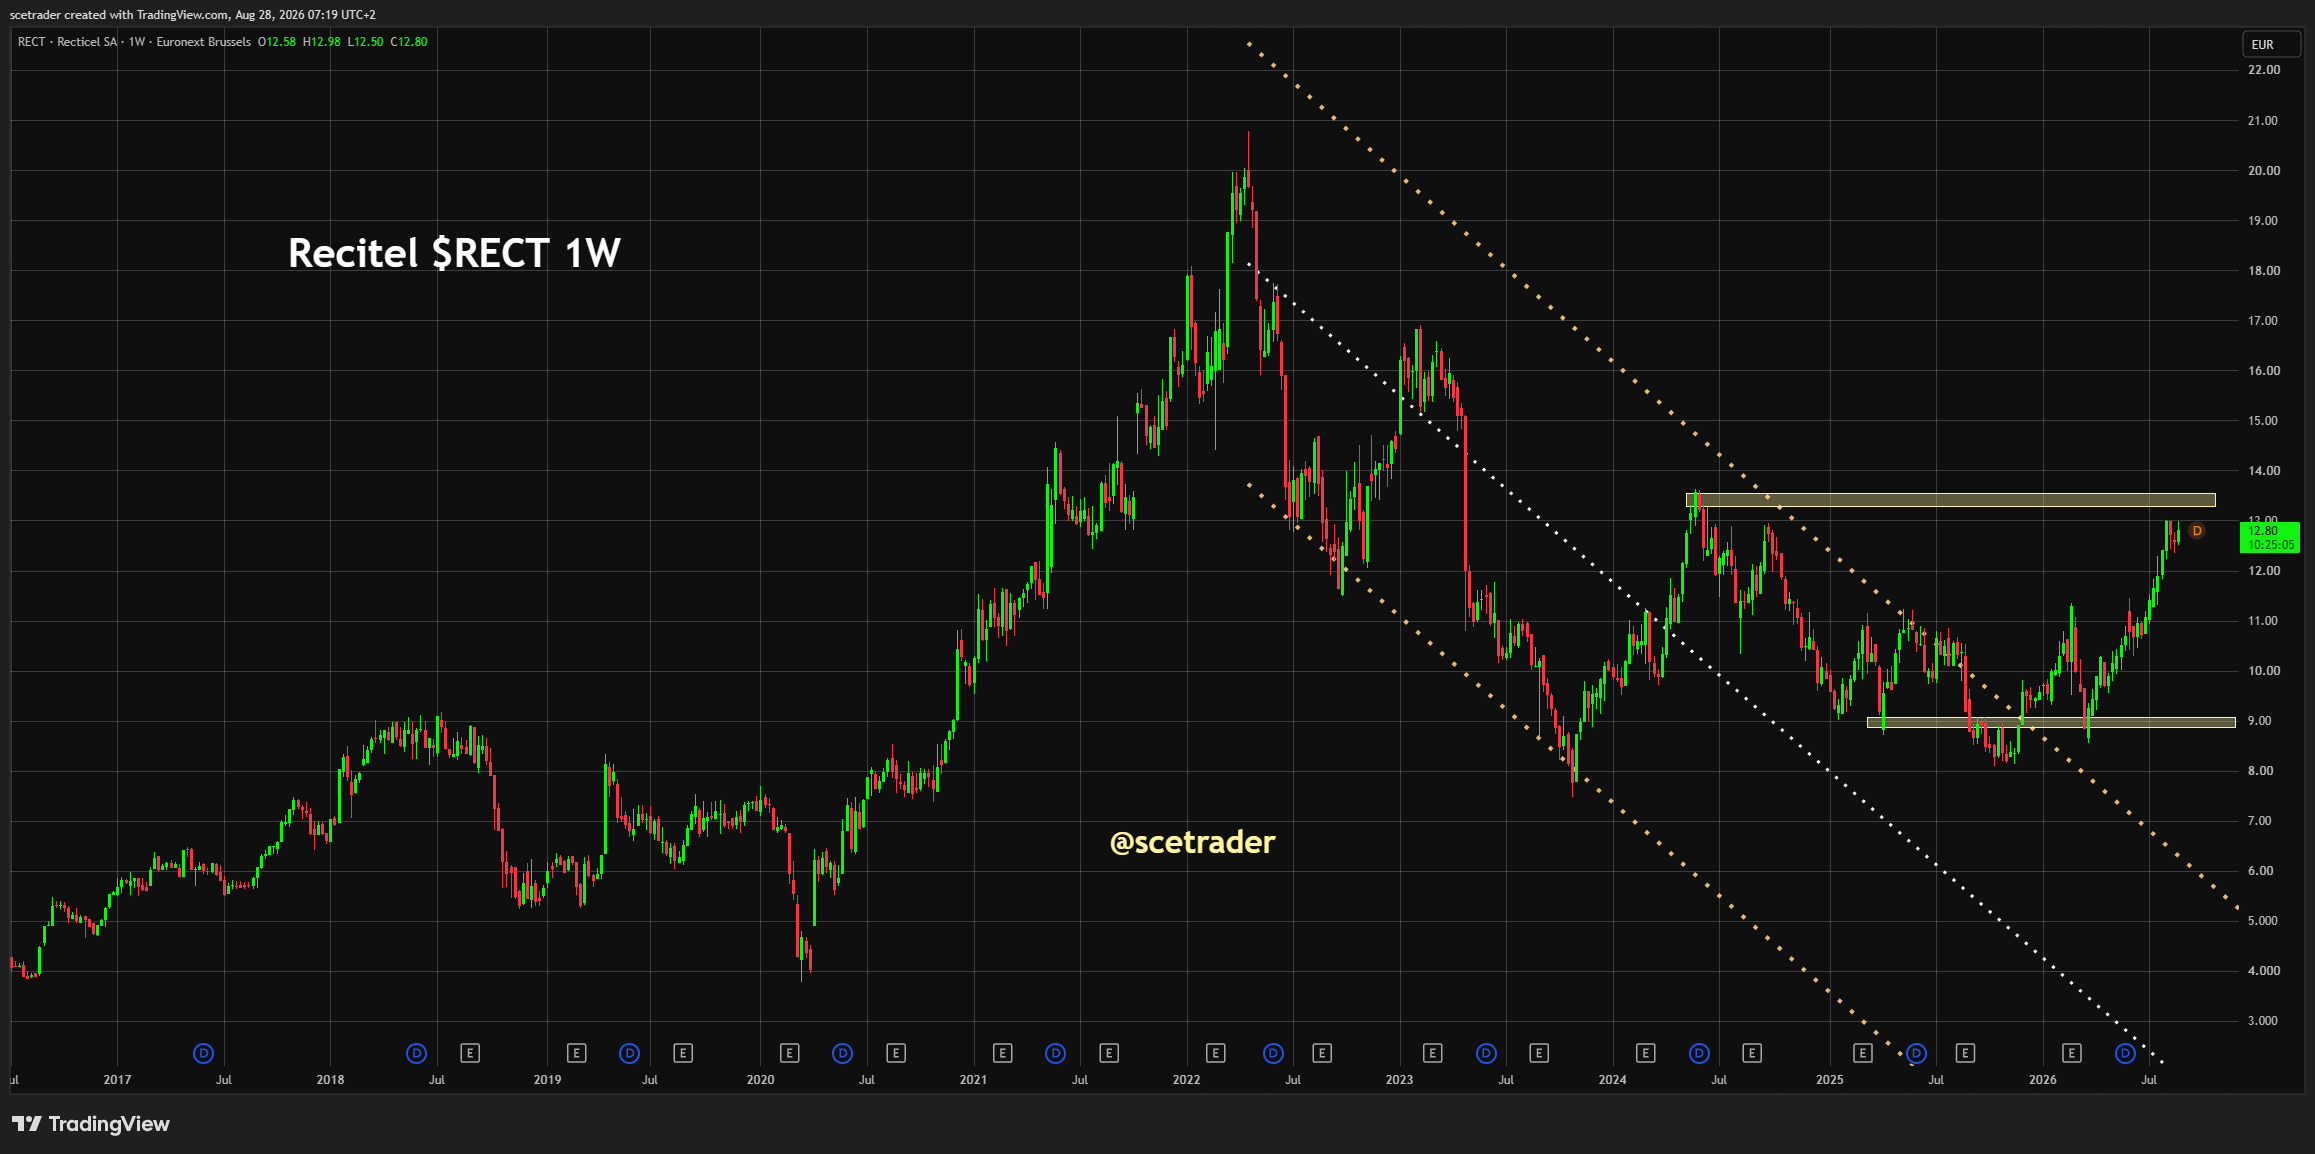
Onze visie op Recticel vraagt om duidelijke timingdiscipline. Operationeel is dit een sterk rapport. De onderneming groeit harder, de marges verbeteren en de outlook voor 2026 geeft beleggers meer vertrouwen in de rest van het jaar.
Als wij het aandeel zouden hebben, zouden wij het vasthouden. De cijfers bevestigen dat Recticel beter draait en dat de strategie rond isolatie, hogere toegevoegde waarde en downstreamproducten resultaat begint op te leveren. Vooral de combinatie van volumegroei, betere mix en hogere productiviteit maakt het verhaal sterker.
Wij zouden op dit moment echter niet bijkopen. De reden is de koerspositie. Het aandeel nadert weerstand en na een positieve reactie kan de markt eerst willen testen of die weerstand echt wordt doorbroken. Voor bestaande aandeelhouders is vasthouden logisch, maar voor nieuwe koopkracht is het risico-rendement vlak onder weerstand minder aantrekkelijk.
Er is wel kans op een hogere start of verdere positieve reactie. De outlook is namelijk sterk. Recticel geeft aan dat het betere tempo uit de eerste jaarhelft in grote lijnen kan worden doorgetrokken naar heel 2026. Dat is belangrijk, omdat beleggers dan niet alleen naar een goed kwartaal kijken, maar naar een mogelijk beter winstjaar.
De nuance zit vooral in de samenstelling van het resultaat. De kernactiviteiten verbeteren duidelijk, terwijl Ascorium nog een negatieve impact geeft via discontinued operations. Voor beleggers is daarom vooral de operationele lijn van Recticel belangrijk: omzetgroei, margeverbetering, hogere productiviteit en de vraag of die trend in de tweede jaarhelft zichtbaar blijft.
Strategisch is Recticel interessanter geworden. Het bedrijf zit in isolatie, energie-efficiëntie en bouwgerelateerde oplossingen. Dat zijn markten met structurele steun op lange termijn, maar op korte termijn blijft de bouwcyclus belangrijk. Daarom zouden wij het aandeel vasthouden bij bezit, maar pas bijkopen bij een duidelijke uitbraak boven weerstand of bij een latere correctie.
Cijfers en outlook
Recticel rapporteerde over de eerste helft van 2026 een omzet van €390,1 miljoen, tegenover €335,2 miljoen een jaar eerder. Dat is een stijging van 16,4%. In het tweede kwartaal versnelde de omzetgroei naar 25,6%. De organische omzetgroei bedroeg 8,4% in de eerste jaarhelft en 17,3% in Q2.
De Adjusted EBITDA steeg met 28,9% van €27,7 miljoen naar €35,7 miljoen. De Adjusted EBITDA-marge verbeterde van 8,3% naar 9,2%. Recticel schrijft die margeverbetering toe aan een betere productmix en hogere productiviteit.
De aangepaste operationele winst steeg met 54,5% van €12,0 miljoen naar €18,6 miljoen. De operationele winst steeg van €8,7 miljoen naar €16,9 miljoen. De winst per aandeel uit continuing operations verbeterde van €-0,10 naar €0,18.
De continuing operations lieten een winst van €10,0 miljoen zien, tegenover een verlies van €5,8 miljoen een jaar eerder. Het groepsresultaat werd gedrukt door discontinued operations, vooral door een negatieve nettovermogenswaarde-aanpassing van €25 miljoen rond Ascorium.
De balans blijft beheersbaar. Recticel rapporteerde een net financial debt van €18,6 miljoen, een gearing ratio van 4,7% en een leverage ratio van 0,3.
Voor heel 2026 rekent Recticel op een Adjusted EBITDA van ongeveer €70 miljoen. Het bedrijf geeft aan dat dit neerkomt op het in grote lijnen vasthouden van de groei uit de eerste jaarhelft. Recticel wil daarbij de margeverbetering uit H1 grotendeels behouden.
Operationele versnelling krijgt meer gewicht
Het sterkste punt in het rapport is dat de groei niet alleen uit hogere omzet komt. Recticel laat ook betere marges zien. Dat is belangrijk, omdat beleggers bij bouwgerelateerde bedrijven vooral willen weten of groei ook winstgevend is.
De CEO wijst op een voorzichtig eerste kwartaal en een veel sterker tweede kwartaal. Recticel kon kostenstijgingen doorrekenen na geopolitieke spanningen in het Midden-Oosten. Ook beperkte beschikbaarheid van grondstoffen uit Azië hielp de verkoopprijzen, vooral bij Insulation Boards.
Dat maakt de prestatie sterk, maar het vraagt in de tweede jaarhelft wel bevestiging. Pricing hielp mee. Als grondstofmarkten normaliseren, moet Recticel laten zien dat volume, mix en productiviteit de winstgevendheid blijven dragen.
Positief is dat smart performance en downstreamproducten een groter deel van de omzet vormen. Dat past bij de strategie om meer te groeien in activiteiten met hogere toegevoegde waarde.
Weerstand als beslispunt
De koers kan positief reageren omdat de outlook stevig is en de operationele trend duidelijk verbetert. Toch is het technische beeld belangrijk. Wanneer een aandeel na sterke cijfers richting weerstand beweegt, wordt het koopmoment gevoeliger.
Een doorbraak boven weerstand zou bevestigen dat de markt het betere operationele verhaal echt wil herwaarderen. Dan wordt het aandeel technisch sterker en neemt de kans toe dat de stijging kan doorzetten.
Blijft de koers tegen weerstand hangen, dan kan de eerste reactie vooral leiden tot winstneming. In dat scenario is vasthouden logisch voor wie het aandeel al heeft, maar bijkopen minder aantrekkelijk.
Daarom is dit geen aandeel dat wij na de eerste sprong direct zouden najagen. Het rapport is goed, de outlook is sterk, maar de koers moet nu laten zien dat de weerstand geen plafond blijft.
Katalysatoren
De eerste katalysator is de FY 2026-outlook. Een Adjusted EBITDA-doel van ongeveer €70 miljoen geeft de markt een duidelijk winstanker. Als Recticel dat doel richting de tweede jaarhelft kan bevestigen, kan het vertrouwen verder toenemen.
De tweede katalysator is margebehoud. De markt zal vooral letten op de vraag of Recticel de margeverbetering uit H1 kan vasthouden. Als dat lukt, wordt het winstherstel geloofwaardiger.
De derde katalysator is de Amerikaanse uitbreiding. De fabriek voor insulated panels in Tennessee ligt volgens Recticel op schema voor productiestart in Q4. Dat kan op termijn een nieuwe groeipoot worden.
De vierde katalysator is de verschuiving naar hogere toegevoegde waarde. Als smart performance en downstreamproducten verder aan belang winnen, kan de kwaliteit van de winst verbeteren.
Risico’s
Het eerste risico is dat een deel van de omzet- en margeverbetering samenhangt met prijszetting in een uitzonderlijke grondstoffenomgeving. Recticel geeft zelf aan dat grondstofkosten mogelijk iets kunnen dalen, maar waarschijnlijk op hoge niveaus blijven.
Het tweede risico is de bouwmarkt. Recticel verwacht een lichte verbetering, maar de bouw blijft cyclisch. Als de bouwactiviteit zwakker blijft dan verwacht, kan dat volumes en productmix raken.
Het derde risico is Ascorium. De negatieve aanpassing raakt vooral discontinued operations, maar beleggers zullen willen zien dat de laatste grote desinvestering wordt afgerond.
Het vierde risico is de koers zelf. Een sterke outlook kan voor een hogere start zorgen, maar als het aandeel direct tegen weerstand aanloopt, wordt het korte-termijnmoment minder aantrekkelijk.
Conclusie
Recticel levert operationeel een sterke eerste helft af. De omzet stijgt, de Adjusted EBITDA groeit harder dan de omzet en de marge verbetert. De outlook voor FY 2026 is sterk, omdat het bedrijf rekent op ongeveer €70 miljoen Adjusted EBITDA en de H1-verbetering grotendeels wil vasthouden.
De kernactiviteiten laten duidelijke verbetering zien. Ascorium drukt het totaalbeeld via discontinued operations, maar verandert niets aan de operationele versnelling binnen de voortgezette activiteiten.
De komende fase draait om bevestiging. De outlook kan een hogere start ondersteunen, maar de koers nadert weerstand. Daardoor ligt de beste aanpak bij vasthouden als het aandeel al in portefeuille zit, terwijl bijkopen pas aantrekkelijker wordt bij een duidelijke uitbraak of een betere correctie.
English version
Recticel: strong outlook, but resistance determines the entry point
No time to read the full article? Use the five bullets below for the key points.
■ Recticel reported a strong first half, with clear operational acceleration.
■ The full-year 2026 outlook is solid and points to continuation of the improved earnings pace.
■ If we owned the stock, we would hold it.
■ We would not add now, because the share price is approaching resistance.
■ There is a chance of a higher open, but for additional buying we want a breakout or a better pullback first.
Recticel delivered a strong update for the first half of 2026. The second quarter showed clear acceleration. Growth was broad-based across key geographies and came from both Insulation Boards and Insulated Panels.
Recticel also reported that the US expansion is progressing as planned and that the new recycling plant in Belgium has started production. The report is therefore not only about better numbers, but also about execution of the strategic growth plans.
Investment view
Our view on Recticel requires clear timing discipline. Operationally, this is a strong report. The company is growing faster, margins are improving and the 2026 outlook gives investors more confidence for the rest of the year.
If we owned the stock, we would hold it. The numbers confirm that Recticel is performing better and that the strategy around insulation, higher value-added products and downstream activities is starting to deliver. The combination of volume growth, better mix and higher productivity makes the story stronger.
We would not add at this point, however. The reason is the share price position. The stock is approaching resistance and after a positive reaction the market may first want to test whether that resistance can actually be broken. For existing shareholders, holding makes sense, but for new buying power the risk-reward just below resistance is less attractive.
There is a chance of a higher open or further positive reaction. The outlook is strong because Recticel indicates that the better pace from the first half can broadly be carried into full-year 2026. That matters because investors are not only looking at a good quarter, but at a potentially better earnings year.
The nuance lies mainly in the composition of the result. The core activities are clearly improving, while Ascorium still has a negative impact through discontinued operations. For investors, the key operational line is therefore most important: sales growth, margin improvement, higher productivity and whether that trend remains visible in the second half.
Strategically, Recticel has become more interesting. The company is active in insulation, energy efficiency and building-related solutions. These markets have structural long-term support, but the construction cycle still matters in the short term. We would therefore hold the stock if owned, but only add after a clear break above resistance or after a later pullback.
Numbers and outlook
Recticel reported first-half 2026 sales of €390.1 million, compared with €335.2 million a year earlier. That is an increase of 16.4%. In the second quarter, sales growth accelerated to 25.6%. Organic sales growth was 8.4% in the first half and 17.3% in Q2.
Adjusted EBITDA rose 28.9% from €27.7 million to €35.7 million. The Adjusted EBITDA margin improved from 8.3% to 9.2%. Recticel attributes the margin improvement to a better product mix and higher productivity.
Adjusted operating profit increased 54.5% from €12.0 million to €18.6 million. Operating profit rose from €8.7 million to €16.9 million. EPS from continuing operations improved from €-0.10 to €0.18.
Continuing operations delivered profit of €10.0 million, compared with a loss of €5.8 million a year earlier. The group result was weighed down by discontinued operations, mainly due to a €25 million negative net asset value adjustment related to Ascorium.
The balance sheet remains manageable. Recticel reported net financial debt of €18.6 million, a gearing ratio of 4.7% and a leverage ratio of 0.3.
For full-year 2026, Recticel expects Adjusted EBITDA of around €70 million. The company says this implies broadly continuing the growth from the first half. Recticel also aims to broadly sustain the margin improvement achieved in H1.
Operational acceleration gains weight
The strongest point in the report is that growth is not only coming from higher sales. Recticel is also showing better margins. That matters because investors in building-related companies mainly want to know whether growth is profitable.
The CEO pointed to a cautious first quarter and a much stronger second quarter. Recticel was able to pass on cost increases after geopolitical tensions in the Middle East. Limited availability of raw materials from Asia also supported selling prices, especially in Insulation Boards.
That makes the performance strong, but it still needs confirmation in the second half. Pricing helped. If raw material markets normalize, Recticel must show that volume, mix and productivity continue to support profitability.
Positively, smart performance and downstream products now represent a larger share of revenue. That fits the strategy of growing more in higher value-added activities.
Resistance as the decision point
The stock can react positively because the outlook is solid and the operational trend is clearly improving. Still, the technical picture matters. When a stock moves toward resistance after strong results, the entry point becomes more sensitive.
A break above resistance would confirm that the market is willing to re-rate the better operational story. The stock would then become technically stronger and the probability of further upside would increase.
If the stock remains capped by resistance, the first reaction may lead to profit-taking. In that scenario, holding makes sense for existing shareholders, but adding is less attractive.
This is therefore not a stock we would chase immediately after the first move. The report is good, the outlook is strong, but the share price now has to show that resistance does not remain a ceiling.
Catalysts
The first catalyst is the FY 2026 outlook. An Adjusted EBITDA target of around €70 million gives the market a clear earnings anchor. If Recticel can confirm that target toward the second half, confidence can increase further.
The second catalyst is margin retention. The market will mainly watch whether Recticel can sustain the margin improvement from H1. If it can, the earnings recovery becomes more credible.
The third catalyst is the US expansion. The insulated panels plant in Tennessee is on schedule for production start in Q4, according to Recticel. That can become a new growth leg over time.
The fourth catalyst is the shift toward higher value-added activities. If smart performance and downstream products continue to gain importance, earnings quality can improve.
Risks
The first risk is that part of the sales and margin improvement is linked to pricing in an exceptional raw-material environment. Recticel itself says raw material costs may ease somewhat but are likely to remain high.
The second risk is the construction market. Recticel expects a slight improvement, but construction remains cyclical. If construction activity remains weaker than expected, volumes and product mix can be affected.
The third risk is Ascorium. The negative adjustment mainly affects discontinued operations, but investors will want to see the final major divestment completed.
The fourth risk is the share price itself. A strong outlook can support a higher open, but if the stock immediately runs into resistance, the short-term entry point becomes less attractive.
Conclusion
Recticel delivered a strong operational first half. Sales increased, Adjusted EBITDA grew faster than sales and margins improved. The FY 2026 outlook is strong because the company expects around €70 million of Adjusted EBITDA and wants to broadly sustain the H1 improvement.
The core activities are clearly improving. Ascorium weighs on the total picture through discontinued operations, but it does not change the operational acceleration in the continuing activities.
The next phase is about confirmation. The outlook can support a higher open, but the share price is approaching resistance. That makes holding the right approach if the stock is already in the portfolio, while adding only becomes more attractive after a clear breakout or a better pullback.
Disclaimer Aan de door ons opgestelde informatie kan op geen enkele wijze rechten worden ontleend. Alle door ons verstrekte informatie en analyses zijn geheel vrijblijvend. Alle consequenties van het op welke wijze dan ook toepassen van de informatie blijven volledig voor uw eigen rekening.
Wij aanvaarden geen aansprakelijkheid voor de mogelijke gevolgen of schade die zouden kunnen voortvloeien uit het gebruik van de door ons gepubliceerde informatie. U bent zelf eindverantwoordelijk voor de beslissingen die u neemt met betrekking tot uw beleggingen.


